Fredonia Mining closes $11.5 million bought deal financing
Fredonia Mining Inc. [FRED-TSXV] said Wednesday it has closed a $11.5 million bought deal financing that included the full exercise of the underwriters’ over-allotment option. The amount raised is up from an earlier $10 million target.
The company said it issued 17.7 million common shares priced at 65 cents per share.
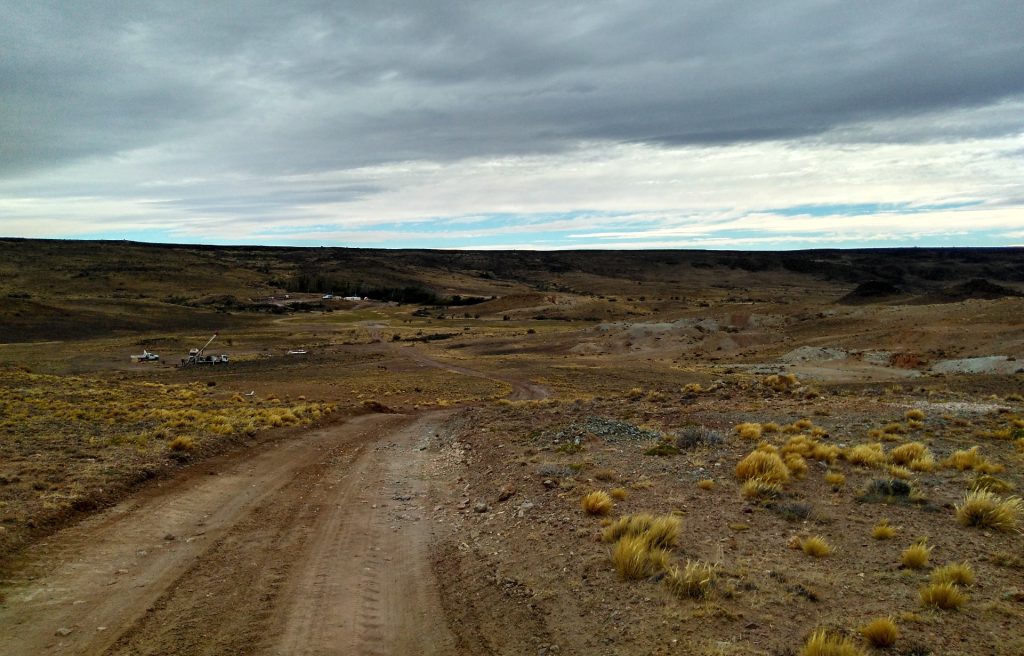
The company said it intends to use the net proceeds from the offering for exploration and advancement of the company’s 100%-owned flagship El Dorado Monserrat gold-silver project in Santa Cruz province, Argentina.
Fredonia shares advanced on the news rising 2.6% or $0.02 to 78 cents. The shares trade in a 52-week range of $1.05 and 31 cents.
The announcement comes after Fredonia recently announced the results of a preliminary economic assessment (PEA) and updated mineral resource estimate for its El Dorado Monserrat project (EDM), which is located near AngloGold Ashanti Ltd.’s [AU-NYSE, ANG-JSE, AGG-ASX] Cerro Vanguardia gold-silver mine.
The PEA envisages average life of mine open pit production of approximately 146,000 ounces of gold equivalent (AuEq) annually over a 17-year lifespan (117,000 ounces of gold and 2.41 million ounces of silver), including approximately 183,000 ounces of AuEq annually during the first five years, reaching 193,000 ounces AuEq in year three, before tapering to a low of approximately 100,000 ounces of AuEq in year 14.
The updated mineral resource estimate includes 126 million tonnes of measured and indicated material grading 0.47 g/t gold and 12.66 g/t silver, containing 1.9 million ounces of gold and 51,4 million ounces of silver (equivalent to 0.68 g/t AuEq or 2.75 million ounces of AuEq). The estimate is supported by nearly 60,000 metres of drilling and extensive surface work, including trenching, and mapping, completed over 15 years of exploration.
The PEA envisages initial capital of approximately US$346 million, consisting of US$143 million for the mine fleet, US$91 million for the process plant and site infrastructure and approximately US$112 million of additional pre-production items and initial working capital.
The company said surface mineralization allows for conventional open-pit truck and shovel mining at a low overall waste to mineralized material ratio of approximately 1:7:1 with processing assumed by heap leaching – based on initial test work and benchmarking with nearby operations – resulting in a cost effective life of mine cash cost of approximately US$1,630 an ounce AuEq.
The scheduled mineral resources are contained within two preliminary operationalized pit designs: Main Veins, in the Northern Corridor, and La Herradura, in the Southern Corridor, located approximately 7.0 kilometres from each other. The mine plan currently excludes the Monserrat West deposit due to a higher associated strip ratio. Monserrat West remains classified as a mineral resource and represents an opportunity for future evaluation at higher metal prices or under a revised development configuration.