Northisle Copper and Gold raises $115 million for B.C. project
Northisle Copper and Gold Inc. [NCX-TSXV] said it has closed a $115 million financing that will be used to advance the company’s Vancouver Island gold-copper porphyry project.
The amount raised included a non-brokered private placement of $5.0 million with Wheaton Precious Metals Corp. (WPM-TSX, WPM-NYSE)
The financing included a brokered offering consisting of 35 million common shares priced at $3.05 each for gross proceeds of $106.8 million, and 1.05 million common shares offered at the issue price on a private placement basis for gross proceeds of $3.2 million. The company also completed a non-brokered offering of 1.63 million common shares offered at the issue price for gross proceeds of $4.99 million. That brought the total number of shares issued to 37.7 million.
On Friday, Northisle shares eased 0.67% or $0.02 to $2.96. The shares trade in a 52-week range of $3.55 and 62 cents.
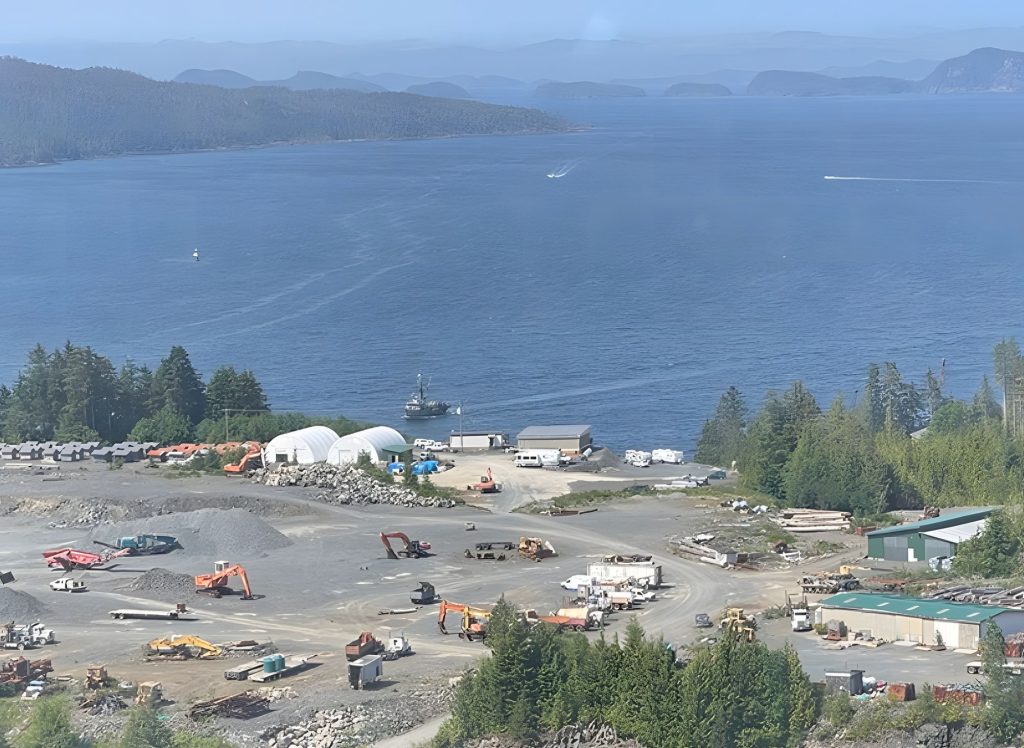
Northisle’s key asset is the North Island Project, which is located near Port Hardy, B.C., on a 34,000-hectare block of mineral titles, stretching 50 kilometres from the now closed Island Copper Mine which was operated by BHP Billiton. Northisle completed a preliminary economic assessment (PEA) for the North Island Project in 2021 and is now focused on advancement of the project through a prefeasibility study, while continuing exploration on the land package.
Northisle’s mineral titles cover most of a Mesozoic-age porphyry copper and gold district and hosts a number of porphyry copper and gold occurrences at varying stages of development. These include the advanced stage Hushamu and Red Dog deposits with NI 43-101 compliant resources, the early-stage Pemberton Hills target and the NW Expo target, as well as several additional porphyry occurrences along the 50-kilometre trend.
A PEA released in February, 2021, contemplates a low strip ratio open pit mining operation which incorporates a 75,000 tonne-per-day concentrator, one that is expected to produce a high-quality copper concentrate with a significant gold by-product as well as a high-grade molybdenum concentrate.
The PEA envisaged a long mine life of 22 years with average annual production of 177 million pounds of copper equivalent (CuEq) over the first six years, including 122 million pounds of copper, 112,000 ounces of gold and 2.7 million pounds of molybdenum.
The PEA also forsees average annual after-tax free cash flow of $321 million during the first six years and $224 million over the life of the operation.
Other highlights included a payback of 3.9 years driven by modest capital expenditures of $1.4 billion due to excellent infrastructure from historical mining and other industrial activity.