Oroco raises $23 million from upsized bought deal financing
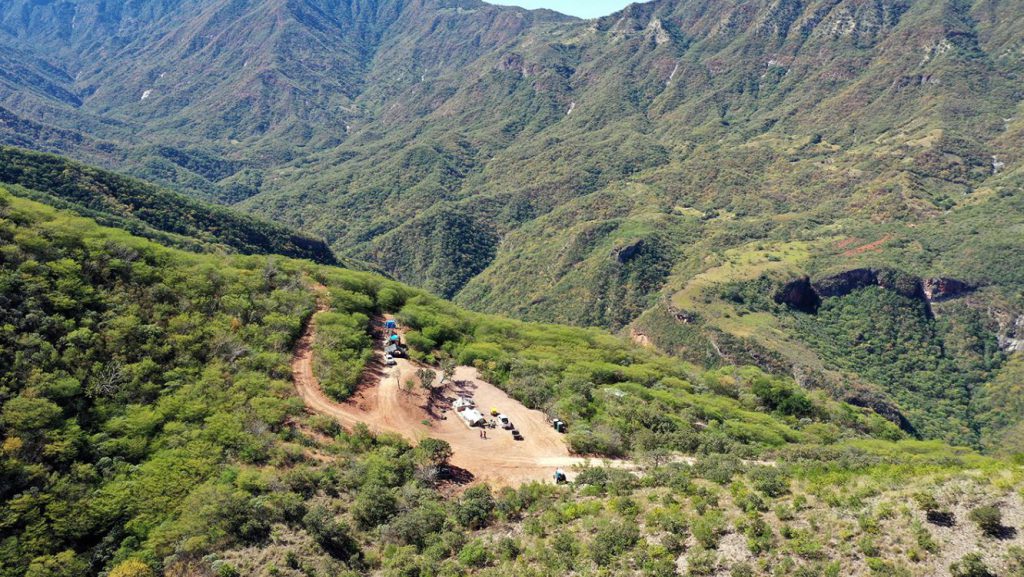
Oroco Resources Corp. [OCO-TSXV, ORRCF-OTC] said it has raised $23 million from an upsized bought deal financing and will use the proceeds to fund pre-feasibility study drilling at the company’s Santo Tomas copper-molybdenum-gold project, located in Sinaloa state, Mexico.
The bought deal offering consisted of 60.5 million units priced at 38 cents per unit. Each unit consists of one common share and one-half of one common share purchase warrant. Each whole warrant entitles the holder to acquire one additional common share at an exercise price of 53 cents until January 15, 2029. The warrants are governed by a warrant indenture dated January 14, 2026, between the company and Computer Trust Company of Canada as the warrant agent. Subject to the final approval of the TSX Venture Exchange, the warrants are expected to begin trading under the trading symbol “OCO.WT” on January 15, 2026.
On Wednesday, Oroco shares eased 8.8% or $0.04 to 41.5 cents. The shares trade in a 52-week range of 67 cents and 23 cents.
Oroco holds an 87% interest in those central concessions, covering 1,173 hectares of the Santo Tomas project. These are the “Core Concessions.’’ The company also holds an 80% stake in an additional 7,861 hectares of mineral concessions that surround and lie adjacent to the Core Concessions.
Back in August, 2024, Oroco announced a revised preliminary economic assessment (PEA) and updated mineral resource estimate (MRE) for the North and South zones at its Santo Tomas project.
The PEA is based on a staged open pit mine and processing plant achieving 60,000 tonnes per day production in year one and expanding to 120,000 tonnes per day in year eight over a 22.6-year mine life.
“Production is preceded by two years of construction and one concurrent year of pre-stripping,’’ the company said.
The plan starts with the use of smaller equipment to provide rapid entry to the mineralized material and maintains a higher-grade feed profile to delay the requirement of an expansion until year eight. Copper equivalent production (CuEq) in the first seven years is forecast at 1.34 billion pounds at a mill feed average grade of 0.51% CuEq.
The initial capital cost is estimated at US$1.1 billion, with sustaining and expansion capital costs pegged at US$1,73 billion. Total life-of-mine payable copper production is expected to reach 4.7 billion pounds.
The PEA mineral resource estimate includes two primary mineralized zones: North Zone and South Zone. These zones display similar mineralization styles but are physically separated by localized post-mineralization faults and material currently identified as waste due to a lack of drilling.
The North Zone pit (sulphide) is estimated to contain 540.6 million tonnes of 0.37% CuEq or 4.46 billion pounds of CuEq. According to the updated MRE, the South Zone pit (oxide) contains an inferred resource of 530.3 million tonnes of 0.35% CuEq or 4.05 billion pounds of CuEq.
Resource World Magazine Inc. has prepared this editorial for general information purposes only and should not be considered a solicitation to buy or sell securities in the companies discussed herein. The information provided has been derived from sources believed to be reliable but cannot be guaranteed. This editorial does not take into account the readers investment criteria, investment expertise, financial condition, or financial goals of individual recipients and other concerns such as jurisdictional and/or legal restrictions that may exist for certain persons. Recipients should rely on their own due diligence and seek their own professional advice before investing.