Seven Decades of Fluorspar, Two Decades of Lessons: Mongolia’s Critical Mineral Test
By Bolormaa Nuurkhuu, B.Sc.
MINING ACCESS
A critical minerals strategy should not begin with theory. It should begin with a real example. Fluorspar is one of them.
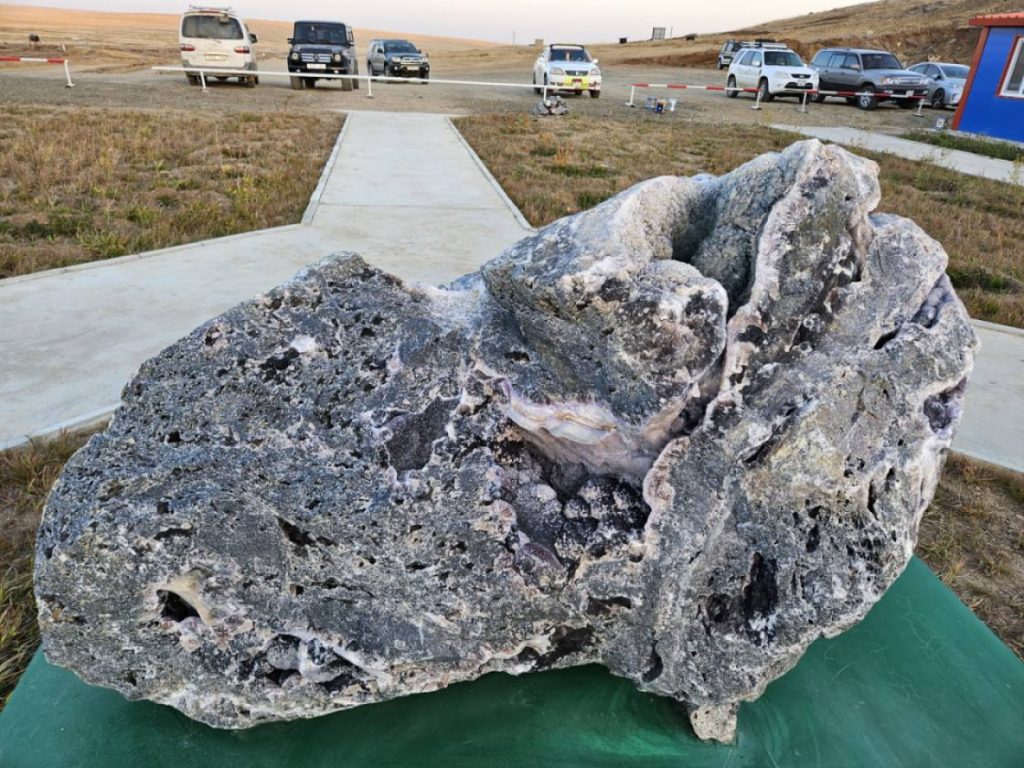
 Mongolia has significant fluorspar resources and seven decades of experience mining, processing, and exporting them a legacy running from the Berkh deposit, opened in 1954, to the Bor-Undur operations today, and ranking the country among the world’s top five producers. This is no minor commodity: fluorspar sits on the critical minerals lists of the United States, the European Union, and China alike. That depth of experience is real. The harder lesson sits with a newer generation of plants. According to the Mongolian Fluorspar Miners, Producers and Exporters Association, some 27 processing plants, large and small, have been built across the eastern fluorspar belt in just the last two decades, most with Chinese investment yet many cannot run at full capacity. The constraints are familiar: unreliable power, interrupted raw-material supply, and weak planning. The resource was never the missing piece, and neither was the experience. The system meant to connect them was.
This is the lesson that should shape the next mineral decade. Naming a mineral “critical” does not create a mine, a railway, a laboratory, a trained workforce, or an offtake agreement. Advanced consumer economies are now publishing their own critical minerals lists and national strategies arguably a bigger shift than the minerals themselves, as governments stop leaving resource security to private markets alone. But a list is policy ambition. Supply is structure. Structure before speed.
 The structural constraints here are sharp. The country is landlocked, dependent on transit states, and burdened by high transport costs. Coking coal and iron ore will, for now, stay tied to the Chinese market, and fuel and energy trade to Russia that is the Mongolia the world already knows. But it is not the whole of the story. The higher-value minerals — tungsten, rare earths, fluorspar tell a different one, and for these the better path runs through third-neighbour partners who can bring investment, technology, and offtake. And this is not a challenge to face alone: through the Ulaanbaatar-based International Think Tank for Landlocked Developing Countries, the country helps frame the shared agenda of resource-rich but landlocked economies.
The geological foundation is more solid than outside observers assume. Systematic exploration began in the 1940s and expanded through the Cold War into tin, tungsten, fluorspar, and molybdenum work that served Soviet needs but built real national geological knowledge. The exploration base, broadly, is already in place. A focused national critical minerals list is now being prepared; the Mongolian Critical Minerals Association, working alongside government, is helping move it toward formal legal approval a timely and important step.
Here, I want to be direct, from two decades of moving Mongolian minerals to market. The instinct in resource policy is to sequence: finish the geological surveys first, then let midstream and downstream follow. In practice that is too slow. Whoever waits for everyone else to move first guarantees the system is never built in time.
The entry that works at the early stage is a team doing three things at once: verifying the resource jointly, combining local knowledge with outside technical experience, and starting to assemble the supply chain from the beginning. A buyer who waits until a deposit is proven and priced, then tries to lock in supply from a landlocked country, arrives too late. The partner who helps prove the resource and is already thinking about how the material reaches an allied market is the one who secures it. The door here is relatively open to partners who come in this way and this early, far more than to those who appear only at the offtake stage, expecting a finished asset.
That openness is the opportunity, but it carries an obligation on our side. The list of what the allied world now needs is long and specific, and much of its copper and molybdenum, titanium and vanadium, graphite and lithium, silver and aluminium falls within the country’s geological range. The real risk is squandering it on the fluorspar pattern: scattered plants, opaque ownership, weak data, no coordination. That is the mistake the country cannot afford to repeat.
Realism about value addition matters too. A smelter sounds attractive, but it brings dependencies power, water, acid handling, logistics, and long-term market commitments. Often an intermediate or semi-processed product is the more investable choice. The aim is not to process everything at home, but to choose the level of value addition where the country stays competitive.
None of this happens through a single government decision. It happens through structure built in parallel better data, stronger planning, trusted third-neighbour relationships, patient cooperation among landlocked countries, and disciplined value-chain thinking. As a Mongolian proverb has it, where there is will, there is a way but the way has to be started together, in parallel, not in sequence. More than investment, what is needed now are partners willing to help build it from the early stage. For those seeking secure, non-concentrated supply, that partnership is where the early advantage lies: structure before speed.